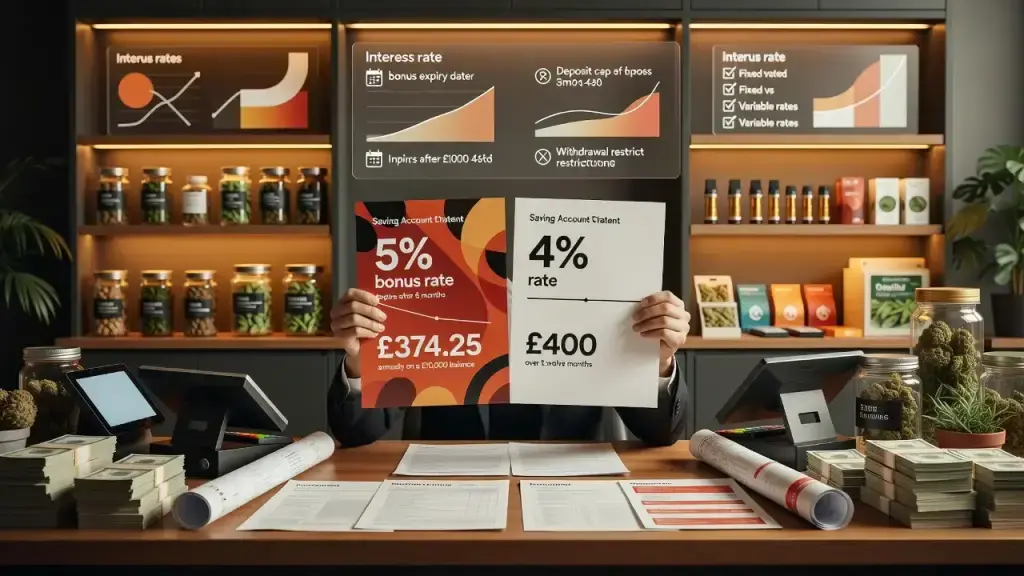
Cannabis retailers sitting on cash reserves - whether from a slow accumulation of post-tax profit or a deliberate buffer against a 280E bill - face a banking puzzle that looks simple but isn't: a business savings account advertising 5 percent can leave an operator worse off than one paying a flat 4 percent. The gap comes down to bonus-rate structures that expire quietly, often within six months, and operators juggling point-of-sale reconciliation, excise tax remittance and payroll rarely have time to track an interest-rate calendar on top of everything else.
Why the Math Works Against Busy Operators
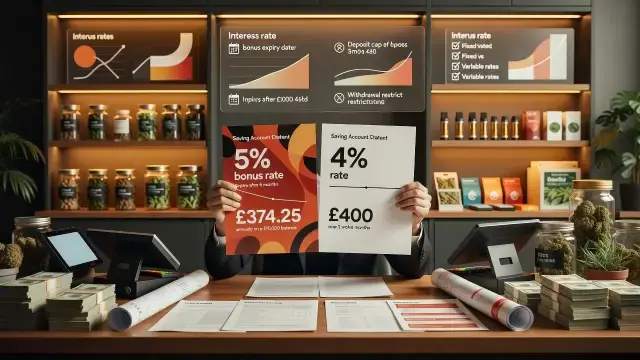
Here's the mechanism. A savings product paying 5 percent for six months, then dropping to a lower standard rate, produces less annual interest than a flat 4 percent account held for the full year - unless the saver remembers to move the money the moment the bonus lapses. On a representative £10,000 balance, the bonus-then-drop account yields £374.25 over a year, compared with £400 from the steady 4 percent option, and £449.88 for someone disciplined enough to switch accounts the day the promotional window closes. That's not a rounding error; it's a real cost of inattention, and it scales with the balance.
For a licensed cannabis business, that inattention tax matters more than it does for an ordinary saver. Many dispensary operators and cultivators already operate with limited banking options, given that federal illegality under the Controlled Substances Act still pushes some financial institutions away from cannabis-adjacent accounts. When an operator does secure a banking relationship - often with a credit union or a fintech partner comfortable serving plant-touching or ancillary businesses - the terms on offer deserve the same scrutiny a compliance officer would give a seed-to-sale discrepancy.
What to Check Before Committing Business Cash
The Moneyfacts analysis points to a short checklist that applies directly to cannabis treasury management: confirm the bonus expiry date, understand what the rate falls to afterward, note any deposit caps above which interest stops accruing, and clarify withdrawal restrictions. A business that needs liquidity for wholesale invoices, delivery manifest payroll, or an unexpected compliance fine cannot afford an account that penalizes withdrawals or locks funds during a bonus period.
- Bonus expiry date and the rate that follows it
- Whether the rate is fixed or variable and subject to change
- Deposit limits above which no interest accrues
- Withdrawal caps that could reduce the advertised rate
Fair enough, a few dollars of foregone interest won't sink a multi-state operator. But for smaller, single-location dispensaries already absorbing the weight of 280E - which disallows standard business deductions for plant-touching companies - every basis point on idle cash counts. The lesson from the consumer savings market translates cleanly: the headline rate is not the number that matters. The number that matters is what lands in the account twelve months later, after the bonus has quietly expired and nobody moved the money.