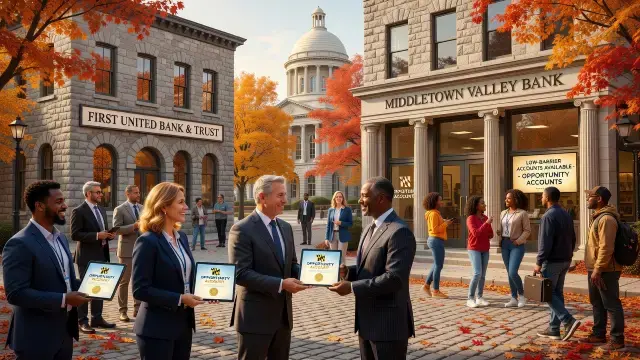
Maryland's Office of Financial Regulation has certified First United Bank & Trust and Middletown Valley Bank as the first institutions approved under the state's new Opportunity Account initiative. The designation marks the formal launch of a program meant to widen access to basic banking tools for residents who have historically struggled to find affordable, low-barrier accounts. For an industry still wrestling with its own banking access problems, the announcement is worth a second look.
Why Cannabis Operators Should Pay Attention
At first glance, a state banking initiative aimed at underbanked consumers has nothing to do with dispensary operations. In practice, though, the two issues sit closer together than they appear. Cannabis retailers have spent years navigating a financial system that treats them as higher risk, often facing fewer banking partners, higher account fees, and limited access to standard commercial lending. Programs like Maryland's Opportunity Account initiative signal how state regulators think about expanding access to mainstream financial products - and that regulatory posture matters to any licensed cannabis business trying to find a bank willing to open a commercial account.
The thing is, banking relationships remain one of the most persistent operational headaches in licensed cannabis retail. Many dispensaries still rely on a small pool of state-chartered banks or credit unions willing to accept cannabis-related deposits, and those relationships come with heavy compliance reporting, enhanced due diligence, and routine account reviews. A state actively certifying new financial institutions for consumer-access programs doesn't automatically translate into cannabis banking relief, but it does show which institutions are willing to work within a more complex compliance framework - information operators and their finance teams track closely.
The Cash-Heavy Reality Behind the Headline
Cannabis remains federally classified in a way that keeps most national banks and card networks at arm's length, which is why so much of the retail side still runs on cash, cashless ATM workarounds, or closed-loop payment apps. That cash dependency creates real friction: inventory shrinkage risk rises, armored transport costs eat into margins, and store managers spend hours reconciling point-of-sale terminals against compliance logs required under seed-to-sale tracking systems like METRC. None of that changes because two community banks earned a new state certification. But it does reinforce a pattern worth watching - Maryland regulators building out financial infrastructure piece by piece, institution by institution, rather than waiting on federal reform that may or may not arrive on any predictable timeline.
For multi-state operators with Maryland footprints, the practical takeaway is less about this specific program and more about signal. State financial regulators willing to certify new banks for one underserved population may, over time, prove more receptive to cannabis-specific banking guidance as well. That's not guaranteed. Fair enough to stay skeptical. But it's the kind of regulatory environment shift that compliance officers and finance leads should log, even when the connection isn't explicit.
What to Watch Next
- Whether additional Maryland banks pursue certification under the Opportunity Account initiative, expanding the pool of institutions comfortable with higher-compliance account relationships
- How state financial regulators balance consumer-protection goals with the needs of cash-intensive, state-legal businesses like licensed dispensaries
- Whether expanded banking access for consumers eventually prompts parallel conversations about cannabis-specific banking guidance at the state level
To put it plainly, this announcement is a consumer-finance story first. But operators who track where state banking policy is heading - rather than just where federal cannabis law currently sits - tend to spot opportunities, and risks, before their competitors do.