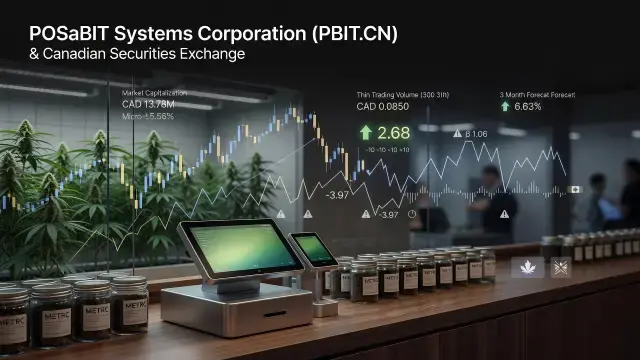
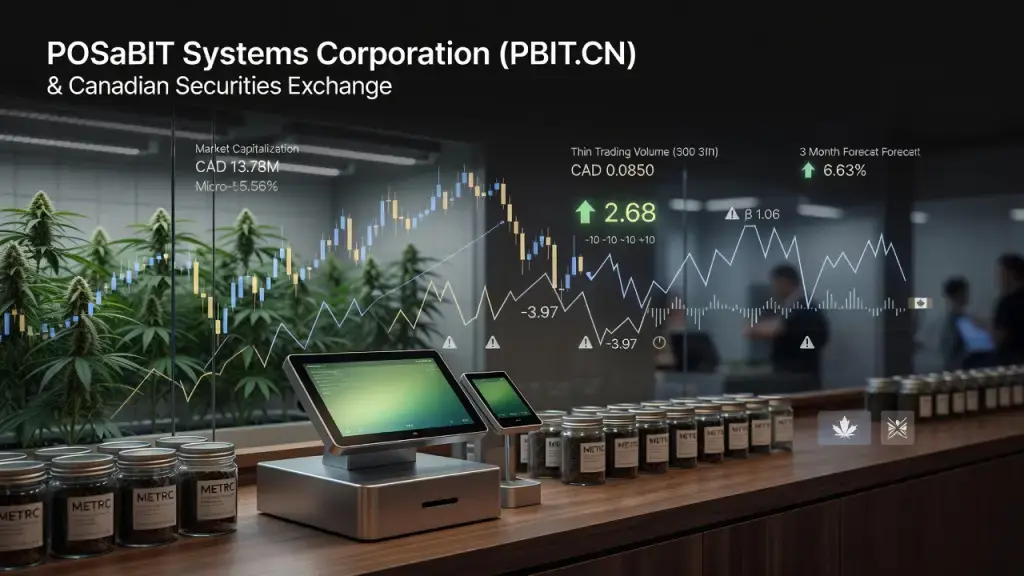
POSaBIT Systems Corporation (PBIT.CN) is sitting in an odd spot: a quantitative model calls it a Buy Candidate, yet the stock just dropped 5.56% in a single session to CAD 0.0850. That gap between a technical score and a sharp down day is exactly the kind of signal small-cap cannabis investors need to read carefully, not react to.
What the Numbers Actually Say
StockInvest.us assigns PBIT.CN a technical score of 2.68 on a scale that runs from -10 to +10, placing it on the positive side but nowhere near a strong conviction call. That score held steady from the prior evaluation, which tells you the model isn't reacting dramatically to the recent price drop. The forecast calls for a 6.63% move upward over three months. Fair enough on paper. But a stock already down 5.56% since its buy signal triggered is not inspiring confidence in the near term, and investors should treat the three-month projection as a probabilistic estimate, not a promise.
The market cap sits around CAD 13.78 million - this is a micro-cap, full stop. Daily volume near 3,000 shares means thin liquidity, wide bid-ask spreads, and price moves that can swing hard on relatively small trade sizes. A negative P/E ratio of -3.97 confirms the obvious: the company isn't profitable yet. Beta of 1.06 suggests volatility roughly in line with the broader market, though for a stock this thinly traded, that beta reading deserves some skepticism.
Why POSaBIT Matters to the Cannabis Retail Supply Chain
POSaBIT operates in the point-of-sale and payment processing corner of the cannabis industry - the plumbing that dispensary operators rely on every single day. Cashless payment solutions, compliant transaction processing, and integration with seed-to-sale tracking systems like METRC are not glamorous, but they're the operational backbone that keeps a licensed retailer's compliance logs clean and its tax filings defensible. When a vendor in this space struggles financially, it's not just a shareholder problem. Dispensary operators who depend on that vendor's terminals and payment rails have a business continuity question to ask themselves.
Cannabis remains federally illegal in the U.S., which means traditional card networks and banks stay largely on the sidelines. That banking gap created the market POSaBIT and similar companies serve. It's also why so many of these payment and POS vendors trade as micro-caps on Canadian exchanges - access to capital markets is tighter when your core customer base operates in a federally restricted product category. Investors should understand this isn't a typical retail tech stock; it's a bet on regulatory evolution as much as on execution.
What Operators and Investors Should Weigh
For dispensary owners evaluating vendors, financial stability matters as much as feature sets. A payment processor or POS provider under financial strain can mean disrupted service, delayed support, or sudden pricing changes - real operational risk for a store that needs its terminals running during business hours, full stop.
- Micro-cap volatility: thin volume means price swings can be outsized relative to news.
- No dividend yield: this is not an income play; any return depends entirely on price appreciation.
- Negative earnings: the P/E ratio confirms the company isn't yet generating consistent profit.
- Sector exposure: performance is tied to adult-use and medical cannabis retail growth, state-level licensing trends, and banking access reform.
None of this amounts to investment advice, and a technical score from an automated model shouldn't substitute for a look at the underlying fundamentals, cash position, and customer contracts. For anyone considering PBIT.CN, the honest takeaway is this: the signal says buy, the chart says caution, and the liquidity says proceed carefully.